

This is the latest information on the subject from Marketsandmarkets, whose research suggests that drone detection system manufacturers and solution providers are focusing on improving detection of small, low-flying, and autonomous drones across different operating environments. Companies are developing compact radar, RF, EO/IR, acoustic, and multi-sensor systems that can support fixed, portable, vehicle-mounted, maritime, and elevated deployments.
They are also improving sensor fusion, RF signal analysis, geolocation, along with AI-based classification to distinguish drones from birds and other objects and reduce false alerts. As users require wider coverage and faster deployment, companies are investing in modular system designs, software-based processing, and automated sensor integration to simplify deployment and support different drone detection requirements.
Localised detection are smaller and require less infrastructure
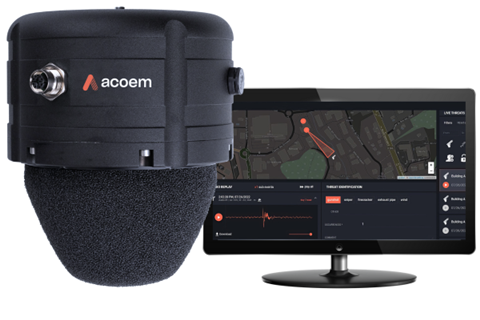
The short range (<1 km) segment addresses localised drone detection requirements where monitoring is focused on the immediate area around a facility, asset, or personnel. These systems are relevant for public venues, prisons, government buildings, temporary military positions, commercial facilities, and other locations where drones may approach at low altitude and close distance. Short-range detection can use RF sensors, EO/IR cameras, acoustic sensors, compact radar, or combinations of these technologies. Portable and man-portable systems are also commonly suited to this range because they can be positioned close to the area requiring surveillance. Short-range systems can provide operators with information on nearby drone activity without requiring the larger sensors and infrastructure associated with longer-range coverage. Improvements in compact sensors, signal processing, and automated target classification are supporting more practical short-range detection across fixed and mobile deployments.
Sensor fusion & geolocation technologies to see strong growth
The sensor fusion & geolocation software segment is expected to register the highest growth in the drone detection market, by offering, from 2026 to 2031. The segment is supported by increasing use of multi-sensor detection systems that generate information from radar, RF, EO/IR, acoustic, and other sensors. Sensor fusion software combines these inputs to create a common drone track and helps reduce duplicate or conflicting detections. Geolocation software determines the position of detected drones and, where supported by RF data, can also help locate their controllers. These capabilities are becoming more relevant as operators monitor multiple drones and larger areas around military facilities, airports, borders, critical infrastructure, and other restricted locations.
North America leads the growth path
North America is, according to the research, expected to register the highest growth in the drone detection market during the forecast period. Growth is supported by increasing requirements to detect unauthorised drones around military installations, airports, borders, government facilities, critical infrastructure, and public areas. The US and Canada are expanding the use of radar, RF, EO/IR, and multi-sensor systems to identify and track small and low-flying drones. Government programmes related to counter-drone operations and protection of domestic infrastructure are also creating requirements for fixed-site, portable, vehicle-mounted, and elevated detection systems.
Key players
Some of the major players in the drone detection market and mentioned within the research include businesses such as, Leonardo DRS, SRC, Saab, Hensholdt, and Echodyne. These companies are deploying organic and inorganic strategies, including product development, partnerships, collaborations, contracts, agreements, and acquisitions, to expand their drone detection capabilities along with geographical presence.

 Global